“Save your money” is too vague to guide a child. A visible goal turns saving into a series of choices: what the child wants, how much it costs, what money may arrive and what they will do when the plan changes. The exercise can work with real pocket money or pretend tokens.
Choose a goal that belongs to the child
Offer a few boundaries: the goal must be safe, allowed and realistic enough to review within several weeks or months. It might be a book, art material, sports item, gift or experience. Do not make a child save for food, school essentials or adult bills. A family may decide to match part of a goal, but the adult should say exactly what that means.
Build the goal card
- Goal and estimated total cost
- Amount already saved
- Possible money sources, such as allowance, gifts or optional paid jobs
- A small regular amount the child chooses to set aside
- A review date
- A space for price changes or a different choice
CFPB guidance recommends setting a goal, breaking it into small steps and helping children practise those steps. The plan should show progress, not turn saving into a test of character.
Make progress visible
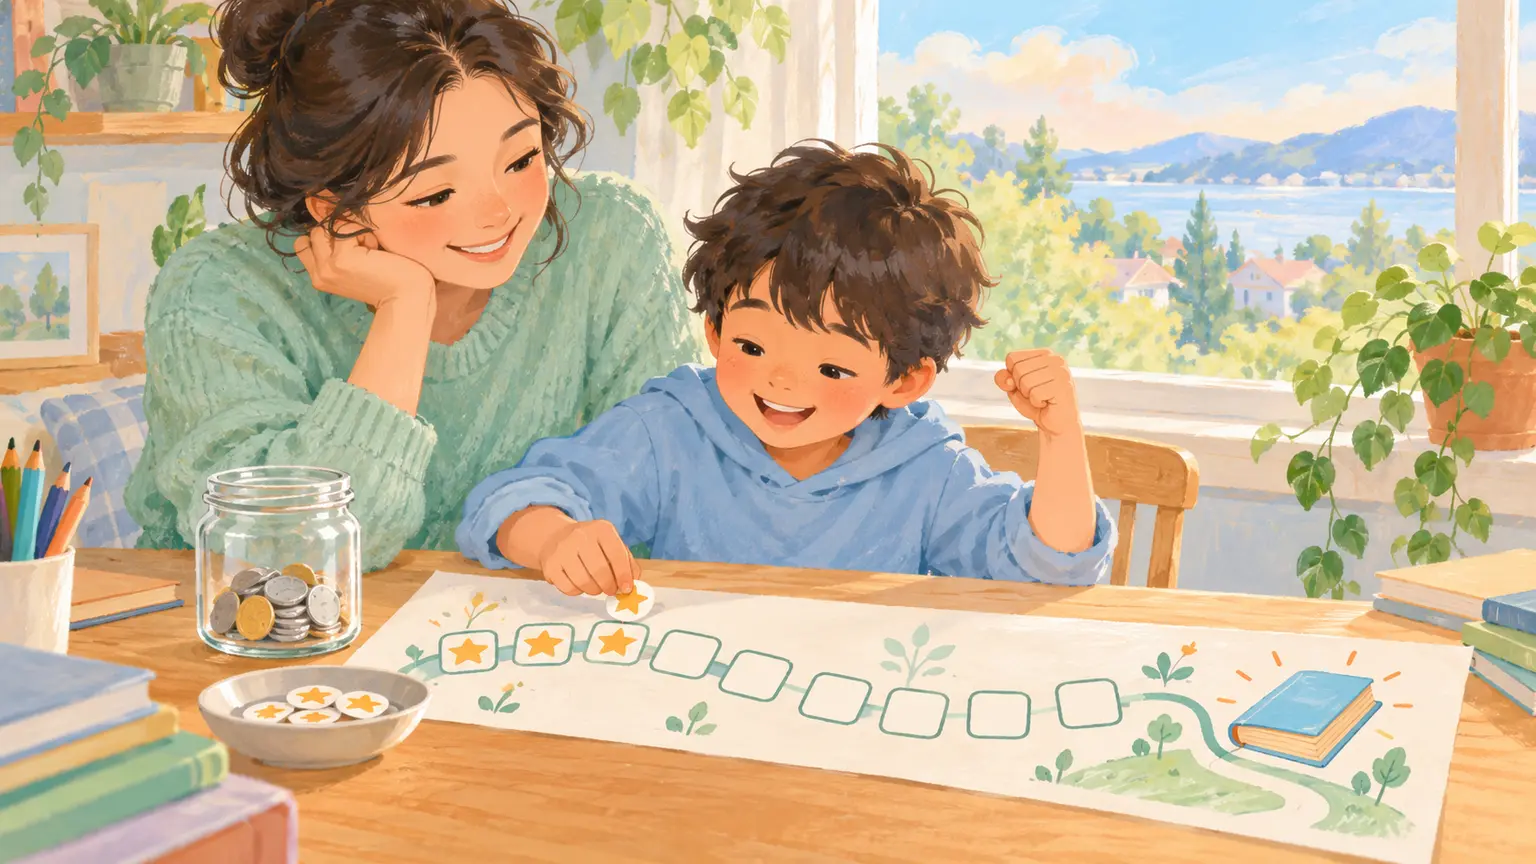
- Draw ten empty boxes or use ten counters.
- Work out what each box represents.
- Mark progress only when money is actually set aside.
- Keep saved money separate from spending money where practical.
- Review before spending from the goal, rather than hiding a mistake.
A preschooler can use pretend counters. School-age children can add amounts. Teens can compare account fees, access and local consumer protections with an adult.
Plan for interruptions
Prices rise, interests change and unexpected needs happen. At the review, offer four honest choices: continue, extend the date, choose a lower-cost version or change the goal. None is failure. If the child spends part of the savings, recalculate from the new balance without lecturing. Ask what made spending feel more important in that moment.
Avoid comparison and pressure
Do not compare siblings’ balances or promise that saving always produces security. Families have different incomes, obligations and access to banks. Protect the child’s privacy and never post their balance online. The useful habit is making a plan, tracking it and adjusting with accurate information.
Related EdCaptain guides: needs and wants in context, comparing the real cost, and planning within a fixed budget.
Use a worked example
Suppose a child wants a game costing 40 tokens and has already saved 12. They expect four tokens every two weeks. The remaining 28 tokens would take seven deposits, or about fourteen weeks. Write that estimate in pencil because income and price may change. Then ask whether the waiting time still feels acceptable.
Add a second scenario: the price falls to 34, or the child receives six gift tokens. Recalculate together. A goal card is not a promise from the adult or a guarantee that the item stays available. It is a current plan based on known numbers.
Make room for more than one purpose
Some children like three containers: spend soon, save for a goal and share. Others find multiple categories confusing. Start with one goal and add complexity only when it helps. A teenager may also want a small emergency buffer for transport or replacing a school item, but adults remain responsible for essentials.
Questions for the review date
- Does the goal still matter to you?
- Was the regular step manageable?
- Did any unplanned spending reveal a missing need?
- Has the price or a better alternative changed?
- What is the next step you choose?
Close the review by updating the card together. The point is not to reward children who can save more. It is to practise choosing, estimating, waiting and revising without secrecy or shame.