By EdCaptain editorial desk · Published
Children already borrow library books, sports equipment and a sibling’s pencil. Those ordinary examples can introduce the central idea of credit: using something now creates an obligation later. The lesson is not “borrowing is bad.” It is “borrow only when you understand what must be returned, when and at what cost.”
Begin with objects
Choose a low-stakes item and make a borrowing card with the item, borrower, owner, condition and return time. Ask what the owner gives up while the item is away. Discuss what happens if it is lost or returned damaged. Do not use treasured or medically necessary items for practice.
Move to pretend money
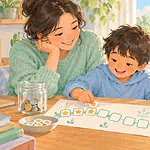
Give the child ten tokens and a fictional choice costing twelve. Offer a loan of two tokens due next round. In a second version, make repayment three tokens to represent an extra cost. CFPB guidance explains that credit is borrowing and that interest can make the borrower pay more. Say clearly that real rates, fees and consumer protections vary.
Use four questions before borrowing
- What am I receiving now?
- What exactly must I return or repay?
- When is it due?
- What will I give up later to meet the promise?
Older children can add a missed-payment fee to the fictional example and notice how small costs compound. Keep arithmetic simple enough that the concept remains visible.
Practise a return plan
Write the due date somewhere the child already checks. Decide how the item will be cared for and what reminder is acceptable. If a child forgets, help them repair the situation: return it, apologise, replace it where appropriate and change the reminder system. Shame does not improve repayment skills.
Important boundaries
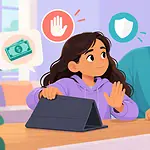
Children should never borrow money online, share an identity document, accept a loan from a stranger or use an adult’s card without permission. Teens should bring any real credit offer, buy-now-pay-later plan or app loan to a responsible adult. Adults must not take credit in a child’s name.
Borrowing can still be useful
Libraries, tool-sharing and carefully managed credit can expand access. The decision depends on purpose, terms and ability to repay. The goal is not fear; it is a pause long enough to understand the promise.
Related EdCaptain guides: needs and wants in context, comparing the real cost, and planning within a fixed budget.
Compare borrowing, sharing and saving
Give the family a fictional need for a tool used once. Option one is to save and buy it. Option two is to borrow it from a neighbour. Option three is to use a library or rental service. Compare access time, responsibility, storage, possible extra cost and what happens if the item is damaged. Borrowing may be the sensible choice when the terms are clear.
Now change the scenario to something used every day. The best option may change. This helps children see that “never borrow” and “always buy” are both weak rules.
Introduce interest without a formula first
Use ten tokens borrowed today and eleven returned later. The extra token represents the cost of borrowing. Then try a longer delay with a larger fictional cost. Older children can calculate a simple percentage, but they should also look for fees, changing rates and the total amount repaid. Do not invite them to compare real adult debts or family balances.
A repair conversation
If a borrowed item is late, practise: “I said I would return this Tuesday. I forgot, and I am sorry. Here it is now. Next time I will put the date on my calendar.” If it was damaged, the adult helps decide a fair repair or replacement plan.
End with the distinction between asking and taking. Permission must come before use, and the owner can say no. A return plan protects trust as much as property.