Children can practise money decisions without seeing the family bank balance or being blamed for what things cost. This 45-minute workshop uses a fictional budget, ordinary choices and one small goal. The purpose is not to find the most frugal child. It is to notice trade-offs and explain a decision.
Prepare a safe, fictional scenario
Choose a pretend amount in your local currency and three categories: something needed now, something enjoyable and something saved for later. Use made-up prices that are easy to compare. Avoid real debt, income, school fees or arguments about past purchases.
Say, “Different families have different resources and priorities. Today we are practising choices, not judging anyone.” A child may use counters, drawings, a calculator or spoken answers.
Warm up with needs, wants and values
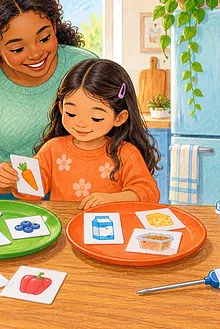
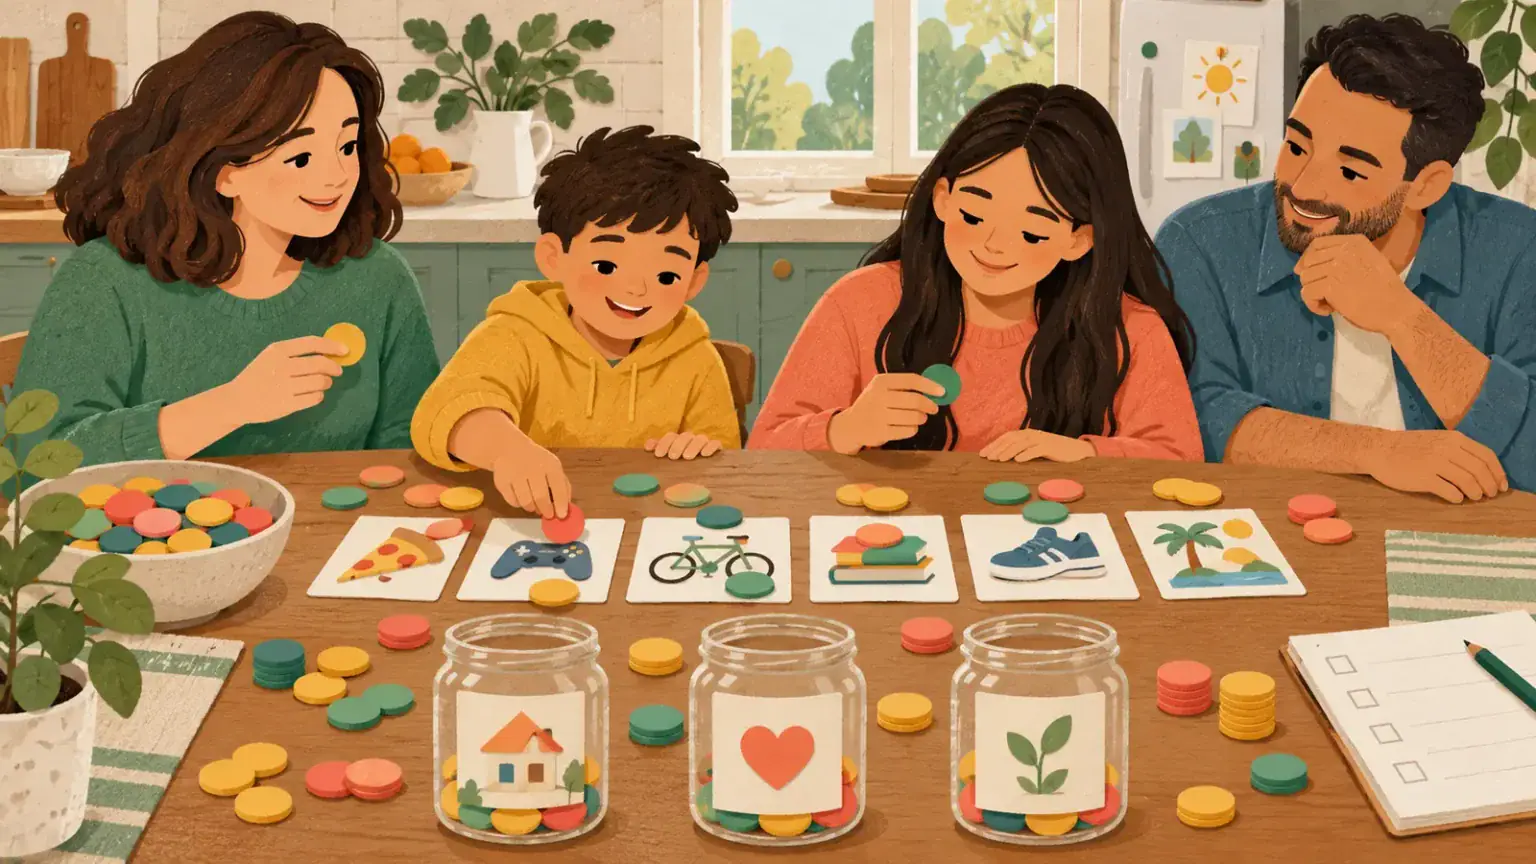
Place six picture cards on the table: food for a meal, transport, a replacement school item, a game, a gift and savings. Ask which decisions depend on context. A coat can be a need in cold weather and irrelevant somewhere hot. A gift can matter because generosity is a family value. The goal is to move beyond a rigid good-or-bad list.
The Consumer Financial Protection Bureau’s Money as You Grow resources connect age-aware activities with planning, saving and financial decision skills. Use that spirit: keep examples concrete and let understanding build over time.
Run the three-round challenge
- Choose: Each person selects how to use the pretend amount and explains one priority.
- Change: Add a new fact, such as a price increase, a broken item or a free alternative. Everyone may revise.
- Save: Pick a future goal and decide what small amount, if any, remains for it.
Do not praise only the person who saves the most. Notice the thinking: “You checked the total,” “You changed your plan when the information changed,” or “You protected something important to you.”
Adapt by age
For ages 6–9, use five or ten counters and two choices at a time. For ages 10–12, add comparison prices and a simple saving goal. Teenagers can consider recurring costs, fees, privacy and the difference between an advertisement and a contract. Keep adults responsible for actual accounts and legal agreements.
Children who find numbers difficult can match pictures to a limited number of tokens. A child who dislikes public explanations can write or point. Financial learning should not become a test of maths speed.
Use language that protects dignity
Replace “We cannot afford anything” with specific, bounded language: “That is not in today’s plan,” or “We are choosing the school item before the game.” Avoid calling a child wasteful, spoiled or irresponsible. If the real answer is no, state it without making the child responsible for adult stress.
EdCaptain’s money-limit script offers language for a difficult moment. A whole-family contribution chart can discuss household work without implying that ordinary care must always be paid. For gentler conversation practice, use the family meal cards.
Finish with one real, low-stakes action
Choose one action the child controls: compare two prices, save for a small goal, wait 24 hours before an optional purchase or ask what a fee means. Adults retain control of accounts, online payments and household budgets. Review the action later with curiosity, not a score.
Repeat with a different kind of choice
On another day, change the scenario from buying to sharing, borrowing, repairing or giving. This prevents the lesson from becoming “money is only for shopping.” A teen might compare a subscription with a one-time purchase; a younger child might decide whether to use tokens now or save them for a shared goal.
If siblings have different allowances or opportunities, use the same fictional materials for everyone. Do not make children disclose gifts, earnings or savings. The useful skill is explaining a trade-off and revising a plan—not proving who owns more.