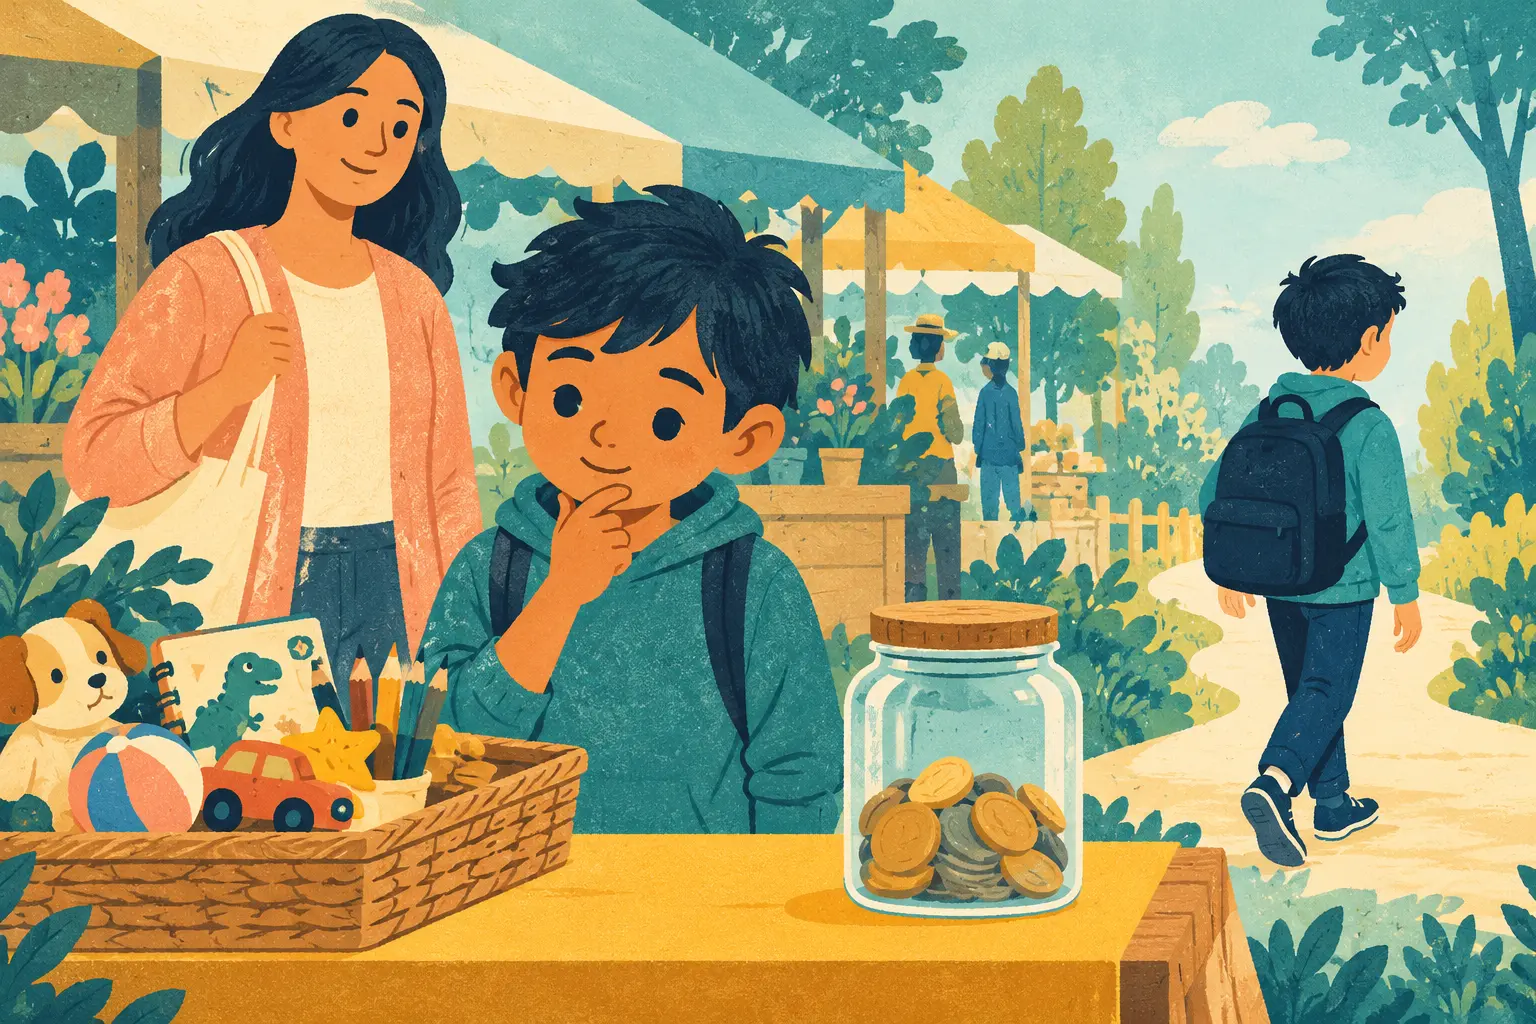
A child clutching birthday money at a shop may feel that not buying something means missing the chance. A teen seeing a limited-time online offer may feel the same pull in a more polished form. Money decisions become easier to learn when children can practise with small, real amounts and a repeatable pause—not when adults deliver a lecture at the checkout.
Separate three legitimate choices
Spend now means the item matters more than the other uses of the money. Save means putting money toward a named future goal. Wait means keeping the option open while checking information or seeing whether the desire lasts. None is automatically virtuous. Saving everything can become fearful; spending everything can erase future options. The skill is connecting the choice to a goal.
Make the money visible
For younger children, use clear jars, envelopes or a simple drawing that shows the amount available and the goal. For older children, a notebook or basic spreadsheet can show income, spending and progress. Use your local currency and realistic prices. If your family does not give an allowance, children can practise with gift money, a small event budget or imaginary amounts during planning.
Avoid paying for every ordinary family contribution. Children can learn both that everyone helps at home and that some agreed extra work may earn money, depending on your family approach.
Ask five questions before buying
- What does it cost, including delivery, fees or things needed to use it?
- What money will remain?
- What other goal would move further away?
- How long do I expect to use or enjoy this?
- Do I need more information or a waiting period?
For a small treat, this can take thirty seconds. For a game, device or other larger purchase, compare prices, quality and return rules from reliable sources. CFPB guidance emphasizes that older children build financial decision skills by comparing options, researching and reflecting on outcomes—not by memorizing one universal spending rule.
Use a waiting rule that matches the purchase
Your family might wait until the next day for an unplanned purchase above an agreed amount. A teen buying online may keep an item in the basket while checking the seller, total price and return terms. The rule should slow urgency without turning every small use of money into an approval battle.
Try: “You may choose after the waiting time. I can help check the information, but I will not choose for you.” This builds on real low-stakes decision practice.
Let the consequence stay proportionate
If a safe purchase disappoints, do not secretly replace the money or repeat “I warned you.” Ask, “What did you learn about the product, the pressure or your goal?” A modest regret can teach more than a perfect adult-controlled outcome. Do step in for scams, age-restricted purchases, unsafe products, coercion or spending that affects essential family needs.
If the child has made a promise or affected someone else, use the repair approach in learning responsibility after a poor choice.
Adapt by age
Ages 6–9 can choose between spending a small amount now and adding it to one clear goal. Use pictures and short time horizons. Ages 10–12 can compare total cost, wait a day and divide money among current use, saving and giving if that reflects family values. Teens can examine subscriptions, recurring costs, advertising tactics, privacy, payment security and the credibility of financial information.
Children vary in impulse control, number understanding and tolerance for delay. Use concrete supports, fewer options and shorter saving goals where needed. Do not shame a child for disability, poverty or having less money than peers. Financial practice should increase agency, not expose private family finances or make a child responsible for adult bills.
Talk about your own choices without making children worry
At the supermarket you might say, “These two meet our need; I’m comparing price per amount,” or “We are waiting because this is not in today’s plan.” Keep the explanation proportionate. Children can learn that adults also make trade-offs without being recruited into financial anxiety.
The broader option-comparison method can help with purchases that have several reasonable choices. The long-term aim is not a child who always saves or never wants things. It is a young person who can pause, check the trade-off and use money in line with their goals.